Everything You Need to Know About Business Owner Policy Hilliard
Protect your Hilliard business with the right Business owner policy Hilliard—get tailored coverage and local expertise from Stanley Insurance Group today.
Why Every Hilliard Small Business Needs a Business Owner Policy
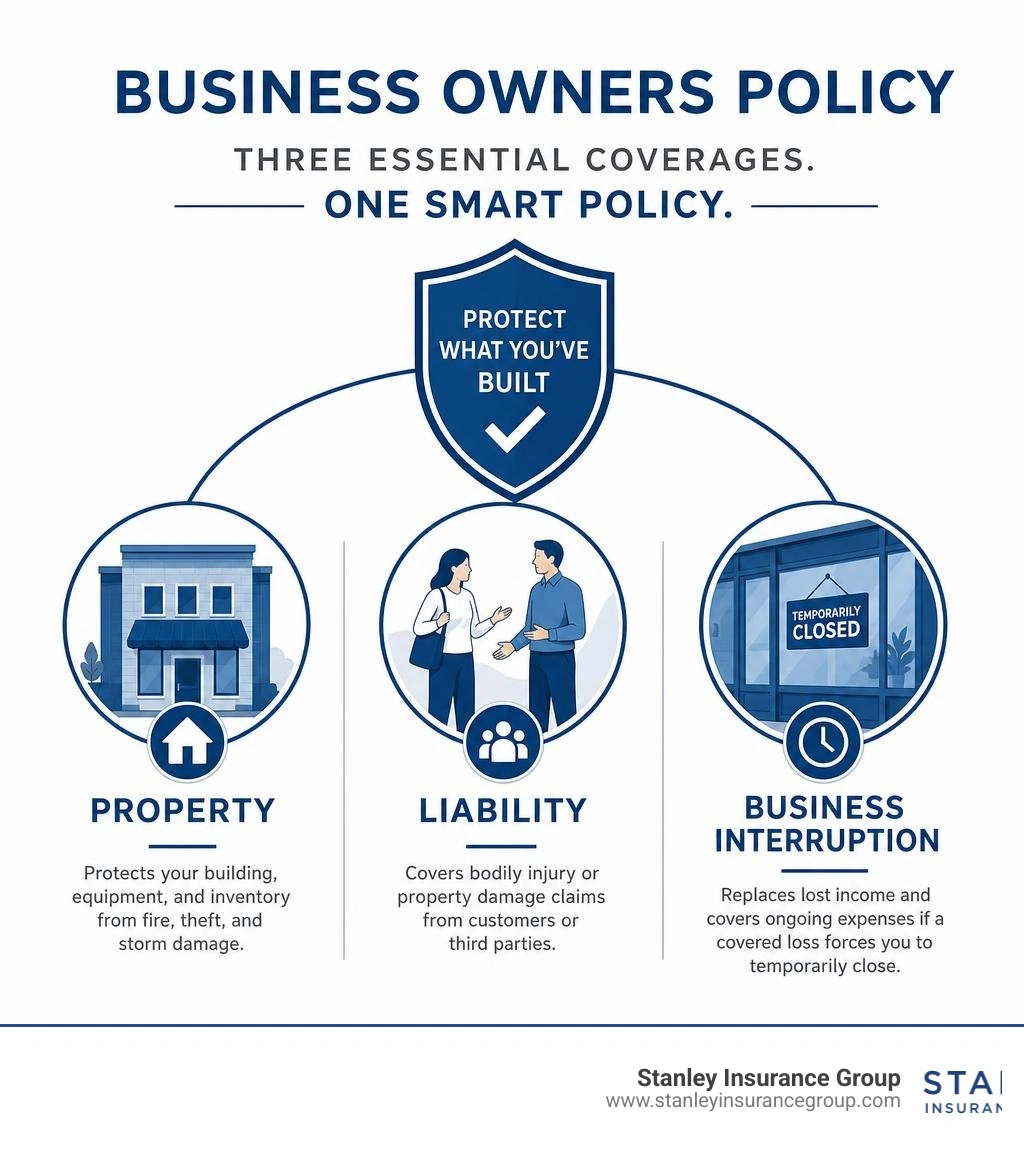
A business owner policy Hilliard business owners rely on combines three essential coverages — commercial property, general liability, and business interruption — into a single, cost-effective policy designed for small and medium-sized businesses.
Quick answer: What does a Business Owner Policy cover in Hilliard?
- Commercial Property — Protects your building, equipment, and inventory from fire, theft, and storm damage
- General Liability — Covers bodily injury or property damage claims from customers or third parties
- Business Interruption — Replaces lost income and covers ongoing expenses if a covered loss forces you to temporarily close
Hilliard is one of the fastest-growing business communities in Central Ohio. The city is home to over 1,200 companies and more than 150 small businesses in the downtown area alone. Events like Pink Friday draw nearly 5,000 visitors to local shops in a single day. That kind of foot traffic is great for sales — but it also means real exposure to liability claims, property damage, and unexpected disruptions.
Running a business here without the right coverage isn't bold. It's a gamble.
A Business Owner Policy (BOP) is the most practical starting point for protecting what you've built — whether you run a boutique on Franklin Street, a consulting firm in a Hilliard office park, or a small restaurant serving the local community.
I'm Brandon Stanley, President of Stanley Insurance Group — a family-owned independent agency that has been helping Hilliard businesses find the right business owner policy in Hilliard since 1984. In this guide, I'll walk you through everything you need to know to choose the right coverage for your business.
What is a Business Owner Policy Hilliard?
When we talk to local business owners about protecting their livelihoods, we often describe the Business Owners Policy as the "Swiss Army knife" of commercial insurance. Instead of managing half a dozen separate policies with different renewal dates and premium invoices, a Business Owners Policy packages your core commercial protections into one neat, simplified bundle.
This type of insurance is specifically engineered for small to mid-sized businesses operating in lower-risk industries. By combining essential property and liability protections, insurance carriers can offer these packages at a significantly discounted rate compared to purchasing each coverage individually. For Hilliard business owners, this means you can keep your hard-earned revenue focused on growth while resting easy knowing your physical and financial assets are secure.
Core Coverages in a Business Owner Policy Hilliard
A standard BOP is built on a foundation of three critical pillars. Each plays a distinct role in keeping your business solvent when the unexpected occurs:
- Commercial Property Insurance: This covers the physical structure of your business premises (if you own it) as well as everything inside it. This includes your inventory, office furniture, specialized equipment, computers, and even exterior signage. Whether a fire breaks out in your stockroom or a severe storm damages your storefront, property coverage helps pay for repairs or replacements. You can learn more about how this works by reading our guide on What is Covered by Standard Commercial Insurance.
- General Liability Insurance: In today's litigious environment, third-party lawsuits can easily bankrupt a growing company. General liability protects your business if a customer, vendor, or delivery person is injured on your property, or if you accidentally damage someone else’s property. It also covers claims related to personal and advertising injury, such as libel, slander, or copyright infringement. For a deeper look into these protections, explore the Business Owners Insurance - Hill Point Insurance resources.
- Business Interruption Insurance: Often considered the most vital coverage for business survival, this component steps in when a covered property loss forces you to temporarily close your doors. If a pipe bursts and ruins your retail shop, business interruption coverage helps replace your lost net income, pays your ongoing rent or mortgage, and ensures you can cover key employee payroll while repairs are underway.
BOP vs. Standalone Commercial Policies
We are frequently asked why a business shouldn't just buy standalone general liability and property policies. The answer comes down to cost, convenience, and coverage gaps.
Purchasing separate policies means you are paying individual administrative fees to carriers, which naturally drives up your total costs. A bundled package, on the other hand, typically results in a 10% to 20% discount on your overall premium. Furthermore, having your property and liability protections under a single policy eliminates the risk of finger-pointing between different insurance companies if a complex claim arises.
To help visualize the differences, we've broken down how a bundled Business Owners Insurance Policy compares to standalone policies:
| Feature / Coverage | Standard Business Owners Policy (BOP) | Standalone Commercial Policies |
|---|---|---|
| Target Business Size | Small to medium-sized ventures | Large, complex, or high-risk enterprises |
| Key Coverages Included | Property, Liability, and Business Interruption | Usually just one specific coverage type per policy |
| Cost Efficiency | Highly cost-effective (bundled discount) | More expensive due to separate policy fees |
| Policy Management | One renewal date, one premium payment | Multiple renewal dates and separate billing |
| Customization | Easily tailored with specialized endorsements | Highly customizable but requires complex underwriting |
For local businesses in Columbus, Dublin, Arlington, and Hilliard, utilizing a bundled approach through a Business Owners Policy (BOP) Insurance - Reynoldsburg, OH specialist is almost always the smartest financial move.
Eligibility and Local Risks for Hilliard Small Businesses
While a BOP is an incredible tool, it isn't a one-size-fits-all solution. Insurance carriers establish specific guidelines to determine which businesses qualify for these package policies. Before we dive into those rules, we always recommend conducting a thorough Business Insurance Risk Assessment to understand your company's unique vulnerabilities.
Who Qualifies for a Business Owner Policy Hilliard?
To be eligible for a business owner policy Hilliard insurers offer, your business must generally meet certain criteria regarding its size, revenue, and industry risk level. While exact rules vary by carrier, standard eligibility requirements often include:
- Business Size: Typically limited to businesses with fewer than 100 employees.
- Physical Footprint: Operations usually must take place in relatively small physical spaces (e.g., offices under 25,000 square feet or retail spaces under 35,000 square feet).
- Revenue Limits: Annual sales are generally capped at a certain threshold, often around $5 million to $10 million depending on the carrier.
- Low-Risk Classification: The business must operate in an industry deemed lower-risk.
Common examples of eligible local businesses include boutique retail shops in Downtown Hilliard, professional service offices (like accountants, lawyers, and marketing agencies), small sit-down restaurants, and light service contractors. If your business fits these parameters, you can easily review options through Business Owner’s Policy (BOP) Insurance | The Hartford or similar top-tier carriers. For a closer look at local eligibility, read our dedicated article on BOP for Small Business Hilliard.
Hilliard-Specific Risks and Events
Living and working in Central Ohio means dealing with specific regional hazards. Our local climate and community calendar introduce unique risks that every Hilliard business owner must plan for.
Take, for example, the annual Pink Friday event. This highly anticipated celebration draws an estimated 4,700 to 5,000 people to Downtown Hilliard to support local shops. While this surge in foot traffic is fantastic for your bottom line, it also dramatically increases your liability exposure. A crowded store increases the risk of a customer tripping over a display or slipping on a freshly mopped floor. If your business hosts or participates in these community gatherings, you need to ask: Does My Commercial Insurance Cover Special Events My Company Holds?
Additionally, Ohio weather is notoriously unpredictable. Hilliard winters bring freezing temperatures, heavy snowfall, and ice storms. A severe freeze can lead to burst pipes in your stockroom, causing thousands of dollars in water damage to your inventory and forcing you to close for repairs. In the summer, severe thunderstorms and high winds can damage roofs and knock out power, leading to spoiled inventory for local food businesses. A robust BOP ensures that both the physical damage and the resulting lost income are covered.
Cost Factors and Optional Coverages to Consider
As business owners ourselves, we understand that managing cash flow is always top of mind. When structuring your commercial coverage, it is important to understand how premiums are calculated and how you can optimize your protection without overpaying.
How Much Does a BOP Cost in Central Ohio?
Because every business is unique, there is no single flat rate for commercial coverage. Instead, underwriters evaluate several key variables to determine your premium. Understanding these factors can help you find ways to lower your costs:
- Industry and Classification: A quiet consulting office in Dublin will naturally pay less than a busy restaurant with open flames and high foot traffic in Downtown Hilliard.
- Location: Your proximity to fire stations, local crime rates, and regional weather patterns all play a role.
- Building Construction and Age: Newer buildings with updated electrical, plumbing, and HVAC systems are less prone to losses and generally cost less to insure.
- Claims History: A track record of clean operations without prior claims shows carriers that you actively manage your risks, which can earn you lower rates.
- Security and Safety Measures: Implementing proactive safety protocols, employee slip-and-fall prevention training, and installing smart security systems or fire alarms can qualify your business for premium discounts.
To learn more about how these factors influence what you pay, take a look at our breakdown of Business Liability Insurance Ohio Cost and our insights on securing Small Business Insurance Columbus Ohio.
Essential Add-On Coverages for Complete Protection
While a standard BOP provides a fantastic foundation, it does have limitations. Fortunately, we can easily customize your policy by adding specialized endorsements to address your specific operational risks:
- Cyber Liability Insurance: If your business processes credit cards, stores customer data, or relies on digital systems, you are a target for cybercriminals. Standard property insurance does not cover digital assets. Adding Cyber Liability Insurance helps cover the costs of data recovery, customer notification, and legal defense following a data breach.
- Professional Liability (Errors & Omissions): If your business provides advice, designs, or professional services, you can be sued if a client claims your work caused them financial harm. A standard BOP does not cover professional mistakes. Adding Professional Liability Insurance bridges this critical gap.
- Commercial Umbrella Insurance: If a catastrophic accident occurs and your primary general liability limits are exhausted, an umbrella policy provides an extra layer of protection, typically adding millions of dollars in additional coverage limits to shield your business from devastating financial loss.
Frequently Asked Questions About Hilliard Business Insurance
Navigating commercial insurance can feel overwhelming. To help you make informed decisions, we’ve answered some of the most common questions we hear from Hilliard business owners. For more guidance on setting up your coverage, check out our guide on How to Choose the Best Business Insurance for Your Company.
Is workers' compensation included in a standard Ohio BOP?
No, workers' compensation is never included in a standard Business Owners Policy. In the state of Ohio, workers' compensation is a monopolistic, legally mandated coverage. This means that if you have even one employee, you must purchase this coverage directly through the Ohio Bureau of Workers' Compensation (BWC) or be certified as a self-insured employer.
While your BOP will handle third-party injuries (like a customer slipping in your store), it will not cover injuries sustained by your own employees while on the job. To make sure you fully understand your liability exposures, we recommend reviewing our Business Liability Insurance Complete Guide.
Can I bundle commercial auto with my business owner policy?
Standard commercial vehicles cannot be directly written into a basic BOP. If your business owns vehicles used for deliveries, client visits, or transporting equipment, you must secure a dedicated Commercial Auto Insurance policy.
However, we can often write your commercial auto policy with the same insurance carrier that provides your BOP. This not only keeps your billing organized but can also qualify your business for multi-policy bundling discounts.
How do I get and compare BOP quotes in Hilliard?
The most effective way to secure competitive rates and robust coverage is by working with an independent insurance agency. Unlike captive agents who can only sell policies from a single company, independent agents work directly for you. We can shop your coverage across dozens of top-rated national and regional carriers to find the perfect fit for your budget and risk profile.
When you sit down with us for a Policy Review and Rate Comparison, we will analyze your current coverages, identify any hidden gaps, and show you real, side-by-side quotes from multiple carriers so you can make an informed choice.
Conclusion
Protecting your Hilliard small business shouldn't feel like a stressful chore. At Stanley Insurance Group, we believe in building lasting relationships with the business owners we protect. We’ve been serving the Hilliard, Columbus, Dublin, and Arlington communities since 1984. As a family-owned independent agency with over 40 years of local tenure, we bring a level of personal service and "concierge touch" that you simply won't find at a giant captive insurer or an online-only platform.
Because we are independent, we have the freedom to shop your coverage across more than 20 of the nation's top insurance carriers — including Nationwide, Progressive, Travelers, Liberty Mutual, Grange, and Safeco. In fact, we are proud to be one of only 100 independent agencies in the entire country with a direct partnership with Geico, giving us unparalleled access to competitive commercial rates.
When you work with us, you aren't calling a distant 1-800 number. You are working with a dedicated local team of experienced professionals:
- Amy leads our Commercial Lines department, helping business owners customize their commercial packages.
- Ana and Sandra are our bilingual Account Specialists, providing expert assistance to our Spanish-speaking clients.
- Kaisen, Ethan, and Chase serve as our trusted Associate Agents, ready to guide you through the quoting process.
Whether you need to secure a new business owner policy Hilliard package, update your home and property coverage, adjust your auto insurance, or secure your family's future with life insurance, we are here to help.
Ready to protect your hard work with a tailored business owners policy? Let's build a relationship that lasts. Get a Quote today, or stop by our Hilliard office to speak with our team in person.
Similar posts