Insurance Review Survival Guide: Real Stories from 100 Independent Agents
Schedule an independent Insurance Review with 100 agents nationwide, including Spanish-speaking help, to find gaps and lower premiums.
Why an Insurance Review Protects More Than Your Premium
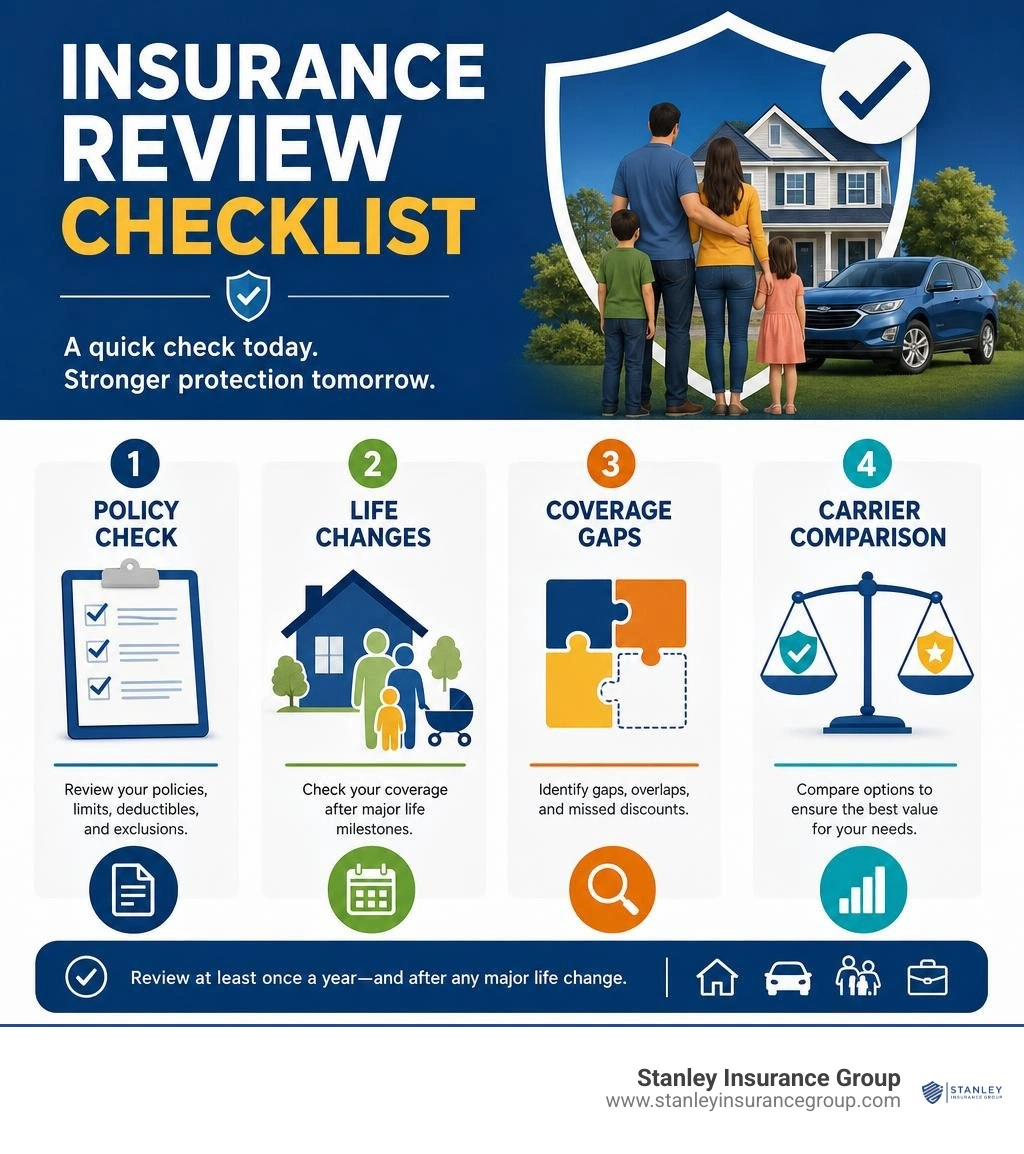
An Insurance Review is a practical checkup of your policies to make sure your coverage, limits, deductibles, and exclusions still fit your life. Review auto, home, life, and business insurance at least once a year, and again after a major change such as buying a home, adding a driver, having a child, renovating, starting a business, or retiring.
Start with these three steps:
- Gather your declaration pages and recent policy statements.
- Compare your current coverage with your home, vehicles, income, assets, and family needs.
- Ask an independent agent to identify gaps, duplicate coverage, missed discounts, and carrier alternatives.
Many people only look at insurance when a claim happens. By then, an outdated liability limit, missing endorsement, or overlooked exclusion can become an expensive surprise. This guide shares the real-world issues independent agents commonly uncover, from home and auto gaps to life policy questions and business risks.
At Stanley Insurance Group, we have built relationships with Hilliard-area families, professionals, and retirees Since '84. There are currently only 100 independent agents in the country with a partnership with Geico, and our agency is part of that group while still helping clients compare coverage options across the market.
You can work with Amy in Commercial Lines, Spanish-speaking Account Specialists Ana and Sandra, or Associate Agents Kaisen, Ethan, and Chase. Spanish-speaking help and agents are available, so clients can get clear answers in the language that feels most comfortable.
I'm Brandon Stanley, President of Stanley Insurance Group, a family-owned independent agency serving clients with home, auto, life, and business protection since 1984. My experience with Insurance Review work centers on helping people understand what they have, spot what is missing, and make confident decisions with a real local agent.
The Comprehensive Insurance Review: What It Is and Why It Matters
An insurance policy is a legal contract designed to protect your financial foundation against catastrophic loss. However, policies are not static assets you can safely buy and store away in a drawer forever. Your career evolves, your property gains value, your family grows, and economic pressures shift market pricing.
Understanding why regular insurance reviews are essential for protecting what matters most starts with recognizing the difference between passive policy renewal and proactive coverage evaluation. A comprehensive insurance audit examines the fine print of every policy you hold—Home & Property Insurance, Auto & Vehicle Insurance, Life Insurance, and Business Insurance—to ensure that your coverage limits match your true asset exposures.
Working with a dedicated independent insurance agent offers distinct advantages over dealing with captive call centers. Captive agents represent a single carrier and can only offer that specific company's underwriting terms and pricing structures. If their carrier's rates spike or underwriting guidelines contract, captive agents cannot pivot your coverage elsewhere.
In contrast, an independent agency operates with an advisory, client-first approach. We benchmark your coverage across more than 20 top-tier insurance carriers, evaluating policy language, endorsements, and claims reputations to build a tailored protection plan that serves your household or business balance sheet.
Life Event Triggers That Demand an Immediate Insurance Review
While we recommend scheduling an annual policy checkup, major life transitions should always trigger an immediate, off-cycle policy evaluation. Failing to update coverage during these milestones creates immediate vulnerabilities:
- Home Renovations and Expansions: Finishing a basement, upgrading a kitchen, or adding an outbuilding directly increases the replacement cost of your home. If your property coverage limit remains pegged to outdated construction estimates, an unexpected total loss could leave you substantially underinsured.
- Marriage and Blended Households: Combining households means merging auto policies, combining personal property schedules, and re-evaluating personal liability. Marriage also unlocks multi-car and companion-policy discounts.
- Welcoming a Child: Expanding your family demands an immediate update to your life and disability protections. Industry standards benchmark adequate death benefit protection at 10 to 12 times your annual salary to replace income, fund future educational expenses, and eliminate household debt.
- Career Advancement and Income Growth: Higher earnings and accumulated savings expand your net worth, making you an attractive target for personal injury lawsuits. Higher liability thresholds and standalone umbrella coverage become essential.
- Adding a Teen Driver: Welcoming a new driver to the road introduces significant liability exposure. Reviewing coverage options ensures you maximize student discounts while securing robust bodily injury and property damage limits.
- Retirement Milestones: Retiring often changes vehicle commute patterns, unlocks mature driver discounts, and shifts financial goals from pure income replacement to wealth preservation and legacy planning.
Independent Agency Networks and Carrier Access
Navigating the modern insurance market requires direct access to multiple underwriting platforms. There are currently only 100 independent agents in the country with a partnership with Geico, and our agency brings that expanded capability directly to Central Ohio clients across Hilliard, Columbus, Dublin, and Upper Arlington.
This expanded carrier network allows our team to compare real-time rates and coverage endorsements across top-tier carriers, ensuring you receive true market transparency. Our office combines this carrier depth with personalized, concierge-level relationship building.
When you connect with our team, you receive direct support from dedicated specialists: Amy leads Commercial Lines for business owners, Associate Agents Kaisen, Ethan, and Chase provide personal lines advisory support, and our Spanish-speaking Account Specialists, Ana and Sandra, ensure full bilingual support. Spanish-speaking help and agents are available across all policy types, giving every client clear, personalized guidance.
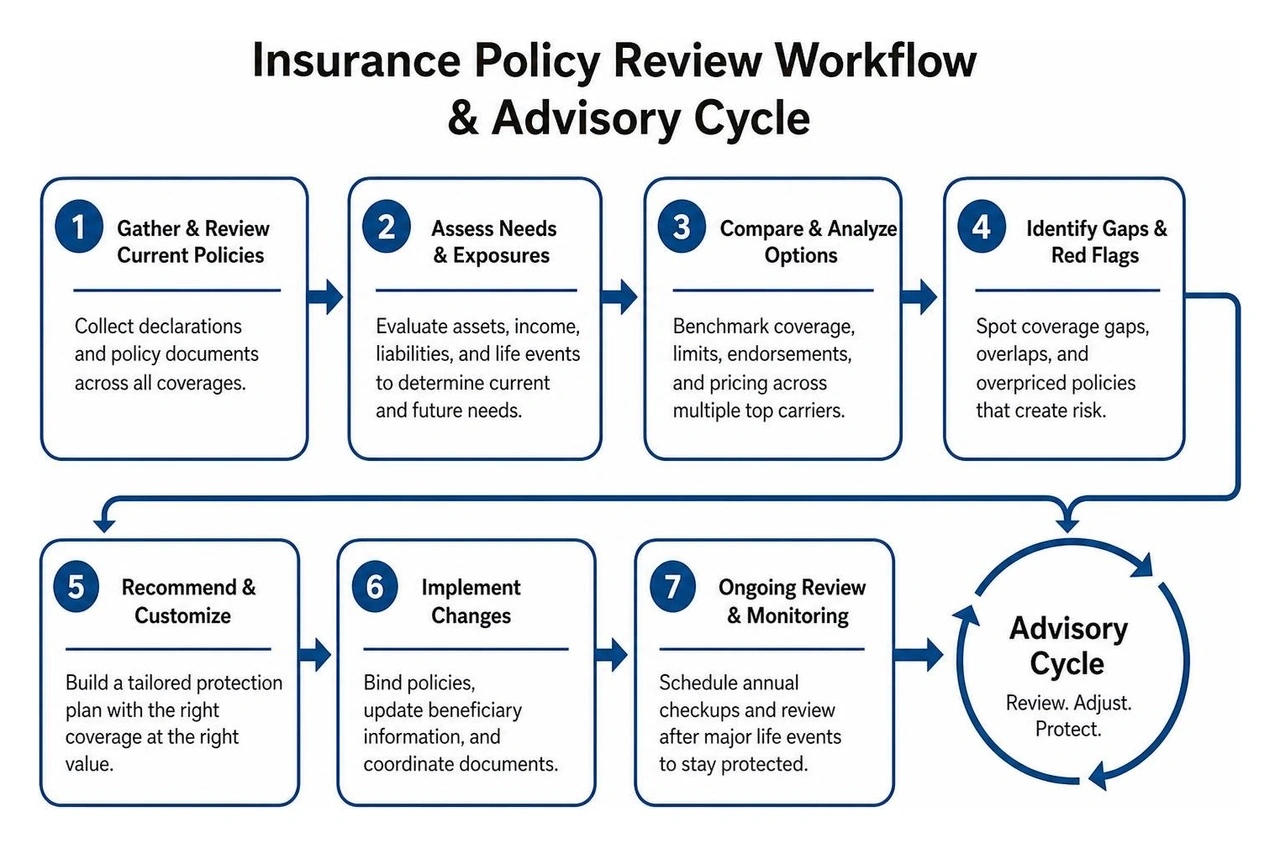
Common Gaps, Overpriced Policies, and Red Flags Identified by Independent Agents
When independent agents conduct deep policy audits, we regularly discover significant coverage lapses that policyholders assumed were covered. Over time, policies fall behind general economic trends. Exploring how inflation affects insurance rates highlights why structural rebuilding costs and auto repair labor often outpace older policy caps, leaving owners on the hook for substantial out-of-pocket balances during a total loss.
Similarly, persistent insurance rate inflation causes many carriers to incrementally increase renewal rates on loyal customers—a practice known in the industry as price optimization. By actively shopping the marketplace and identifying targeted ways to reduce insurance costs, an independent audit can capture multi-policy credits, defensive driving savings, and updated vehicle usage discounts.
A major area where policyholders encounter surprises involves premium rate spikes following a claim. Across the industry, premium rates increase by an average of 32% following an at-fault accident, with surcharges lingering on driving records for three to five consecutive years. If an insurer applies punitive rate increases after a single incident, our independent agents can re-market the risk across competing carriers to find competitive alternative options.
Identifying Underperforming Policies and Rating Discrepancies
A cheap premium means little if the insurer lacks the financial stability to settle claims or routinely denies legitimate requests. During every review, our agents cross-reference carrier financial health with AM Best solvency grades to verify that the underwriting company has the capital reserves needed to weather catastrophic loss events.
Equally critical is the National Association of Insurance Commissioners (NAIC) Complaint Index. An NAIC index score of 1.0 represents the national median; a score significantly higher reveals a carrier that generates disproportionate consumer disputes regarding delayed payouts and claims mishandling. For instance, high-risk, direct-to-consumer auto insurers frequently post elevated complaint indexes—sometimes more than five times the national median—reflecting frequent customer service friction, slow claims handling, and frustrating third-party adjuster delays.
Furthermore, our agents evaluate your deductible structures. Reviewing help with insurance deductible strategies allows clients to strategically raise comprehensive or collision deductibles to lower monthly premiums, provided sufficient emergency cash reserves are in place. Having dedicated insurance help ensures that when a claim arises, you have professional support for help with insurance claims rather than navigating complex adjuster negotiations alone.
Resolving Multi-Policy and Umbrella Coverage Deficits
Carrying disconnected policies across multiple different insurance companies is one of the most common mistakes uncovered in an independent review. Disconnected policies cause two severe problems:
- Lost Multi-Line Discounts: Bundling Home & Property Insurance with Auto & Vehicle Insurance routinely unlocks premium reductions of 15% to 25% across both contracts.
- Dangerous Liability Gaps: If your auto policy carries bodily injury limits of $100,000/$300,000, but your personal umbrella policy requires underlying primary limits of $250,000/$500,000 to activate, a catastrophic auto collision creates a $150,000 personal liability gap that you must pay out of pocket before your umbrella coverage contributes a single dollar.
An independent audit identifies these underlying mismatches, eliminates coverage gaps, and secures comprehensive personal umbrella protection to safeguard your home equity, retirement assets, and future wage earnings against severe legal judgments.
Evaluating Specialized Lines: From Business Portfolios to Life and Pet Coverage
A comprehensive review extends well beyond basic home and vehicle coverage. Business owners, executives, and families require targeted risk evaluations across specialized commercial and individual policies to prevent balance sheet erosion.
For commercial enterprises, Amy leads our Commercial Lines department, structuring comprehensive commercial reviews that analyze general liability, commercial property, inland marine, and cyber liability exposures. When reviewing a company's commercial program, conducting an unbiased policy analysis for businesses regularly uncovers costly operational redundancies.
For instance, companies frequently carry duplicate coverage across separate inland marine and property schedules or hold outdated workers' compensation class codes that inflate payroll audits. Reviewing your commercial risk profile ensures your coverage terms evolve in step with your annual gross revenues, physical footprint, and supply chain dependencies.
Conducting a Cash Value and IUL Insurance Review
Permanent life insurance contracts—including Whole Life, Universal Life (UL), and Indexed Universal Life (IUL)—require regular, specialized diagnostics. Unlike simple term life insurance, permanent policies contain complex internal expense engines that fluctuate with interest rate environments, carrier cost-of-insurance adjustments, and cash allocation performance.
The most critical document for analyzing a permanent life policy is an updated in-force illustration. As highlighted by independent life audits conducted through the Policy Review Center, an in-force illustration reveals the actual health of your policy based on real historical performance rather than initial sales estimates.
Many underperforming permanent policies suffer from historical under-funding. When crediting rates fall below initial projections, internal policy costs slowly eat away at the cash value, eventually creating severe policy lapse risks. Utilizing targeted cash value and IUL policy review diagnostics allows policyholders to determine whether adjusting annual premium contributions can save the policy, or if executing an IRC Section 1035 tax-free exchange into a modern contract with accelerated living benefit riders makes financial sense.
For comprehensive life benchmarking and policy comparisons, independent resources like Life Insurance Review (LIR) provide valuable frameworks for comparing historical performance and ensuring ongoing legacy protection through an existing in-force life policy review.
Specialty and Pet Insurance Policy Considerations
Specialty personal lines, including pet health insurance, require careful scrutiny during an annual household review. Pet insurance policies are indemnity contracts that vary wildly between carriers in their reimbursement mechanics, waiting periods, and exclusions.
When evaluating specialty health coverage for family pets, checking verified owner reviews and rating metrics offers essential insight into how efficiently carriers process high-dollar veterinary claims. Pay particular attention to waiting periods for orthopedic conditions—which can extend up to six months—and confirm whether chronic conditions remain covered throughout the animal's lifetime without punitive renewal surcharges.
Frequently Asked Questions About Insurance Reviews
How often should an individual or business schedule a policy review?
Individuals, families, and commercial business owners should schedule a formal insurance review at least once every 12 months. Aligning your review with annual renewal notices allows you to benchmark incoming rate revisions against competing carrier products before premiums auto-renew.
Additionally, schedule an immediate off-cycle review whenever you experience significant life changes—such as purchasing real estate, undergoing major home renovations, acquiring high-value jewelry or art, altering business operations, or adding a new driver to your household.
What documents are required to complete a thorough review?
To complete a swift and thorough insurance review, gather the following primary documents:
- Policy Declarations Pages: The summary pages for all active Home, Auto, Umbrella, and Commercial policies showing current coverage limits, deductibles, and annual premiums.
- Recent Billing Statements: Verification of current premium schedules, split payments, and active discount endorsements.
- In-Force Illustrations: For permanent life insurance (Whole Life, Universal Life, or IUL), request a fresh in-force illustration from your carrier projecting future cash value and death benefits.
- Property Schedules & Appraisals: Up-to-date appraisals or receipts for scheduled personal property, such as fine jewelry, firearms, collectibles, or specialized business tools.
With these documents in hand, an independent agent can complete a comprehensive multi-policy diagnostic in a matter of minutes.
Can an independent review lower premiums without sacrificing coverage limits?
Yes. An independent insurance review regularly identifies meaningful premium reductions while maintaining or expanding your underlying liability limits. Because independent agencies shop across 20+ top-rated carriers, we leverage competitive underwriting differences to your advantage.
Agents reduce costs by capturing unapplied multi-policy bundling discounts, eliminating outdated or duplicate policy endorsements, optimizing deductible tiers based on your liquid savings, and relocating your coverage to carriers whose risk appetites offer better pricing for your specific demographic profile. For additional strategies on managing rising insurance expenses, explore our comprehensive help with insurance premiums guide and review our practical ways to save on insurance.

Conclusion
A regular insurance review is the single most effective way to eliminate dangerous coverage gaps, capture hidden discounts, and ensure your financial assets remain fully protected against unexpected loss. Reviewing your policies should never feel like an intimidating chore or a high-pressure sales pitch. By taking a proactive look at your declarations pages alongside an experienced, independent professional, you can replace uncertainty with complete financial confidence.
At Stanley Insurance Group, we take pride in delivering a true concierge experience rooted in multi-generational relationship building. Serving the Hilliard, Columbus, Dublin, and Upper Arlington communities Since '84, our family-owned agency combines deep local roots with access to more than 20 leading insurance carriers.
Whether you need to review your Home & Property Insurance, structure Auto & Vehicle Insurance, evaluate Life Insurance needs, or protect your enterprise with comprehensive Business Insurance, our team is here to help. Contact Amy for Commercial Lines, connect with Associate Agents Kaisen, Ethan, or Chase for personal lines coverage, or speak with our Spanish-speaking Account Specialists, Ana and Sandra. Spanish-speaking help and agents are available across all product lines.
Take control of your coverage today. Reach out to our local team to schedule an independent policy review and rate comparison and experience the protection that comes with over 40 years of dedicated independent advocacy.
Similar posts