Cheat Sheet to BOP Insurance for Hilliard Retailers
Protect your Hilliard retail store with a BOP for retail Hilliard—bundle property, liability and business interruption for complete coverage.
Why Every Hilliard Retailer Needs to Understand Their BOP Options
BOP for retail Hilliard stores is one of the smartest coverage moves a local business owner can make. A Business Owners Policy (BOP) bundles property and liability protection into a single policy — and it typically costs less than buying those coverages separately.
Quick answer: What does a BOP cover for Hilliard retailers?
- Property coverage — your inventory, fixtures, and leased space
- General liability — customer injuries, property damage claims, and legal defense
- Business interruption — lost income if a covered event forces you to close temporarily
- Optional add-ons — cyber liability, equipment breakdown, EPLI, and more
A few numbers that put the stakes in perspective:
- Hilliard retail locations see a 12% higher rate of slip-and-fall claims than the national average for similar communities
- Ohio retail businesses average 2.3 property claims per year, with theft and water damage leading the list
- More than 60% of small retailers that suffer a major uninsured loss never reopen
For Hilliard shop owners — whether you run a boutique off Cemetery Road, a pop-up at the Hilliard Market, or a multi-location operation across Central Ohio — having the right BOP in place is the difference between a setback and a shutdown.
I'm Brandon Stanley, President of Stanley Insurance Group, a family-owned independent agency serving Hilliard since 1984, and helping local retailers build the right BOP for retail Hilliard operations is one of the most common conversations we have with business owners. In the breakdown below, I'll walk you through exactly what a BOP covers, where the gaps are, and how to make sure your policy actually matches the risks your store faces in 2026.
Important BOP for retail Hilliard terms:
What is a BOP for Retail Hilliard Store Owners?
At its core, a Business Owners Policy (BOP) is a package deal designed specifically for small to mid-sized businesses. Think of it like a value meal for commercial insurance: instead of purchasing your property protection, liability protection, and loss of income coverage separately, you buy them together under one convenient umbrella.
For retail stores in Hilliard, this bundling is incredibly powerful. Small businesses that opt for a BOP can save an average of 15-25% compared to purchasing separate property and liability policies. This cost-efficiency is a game-changer for local shops trying to keep overhead low while maximizing protection.

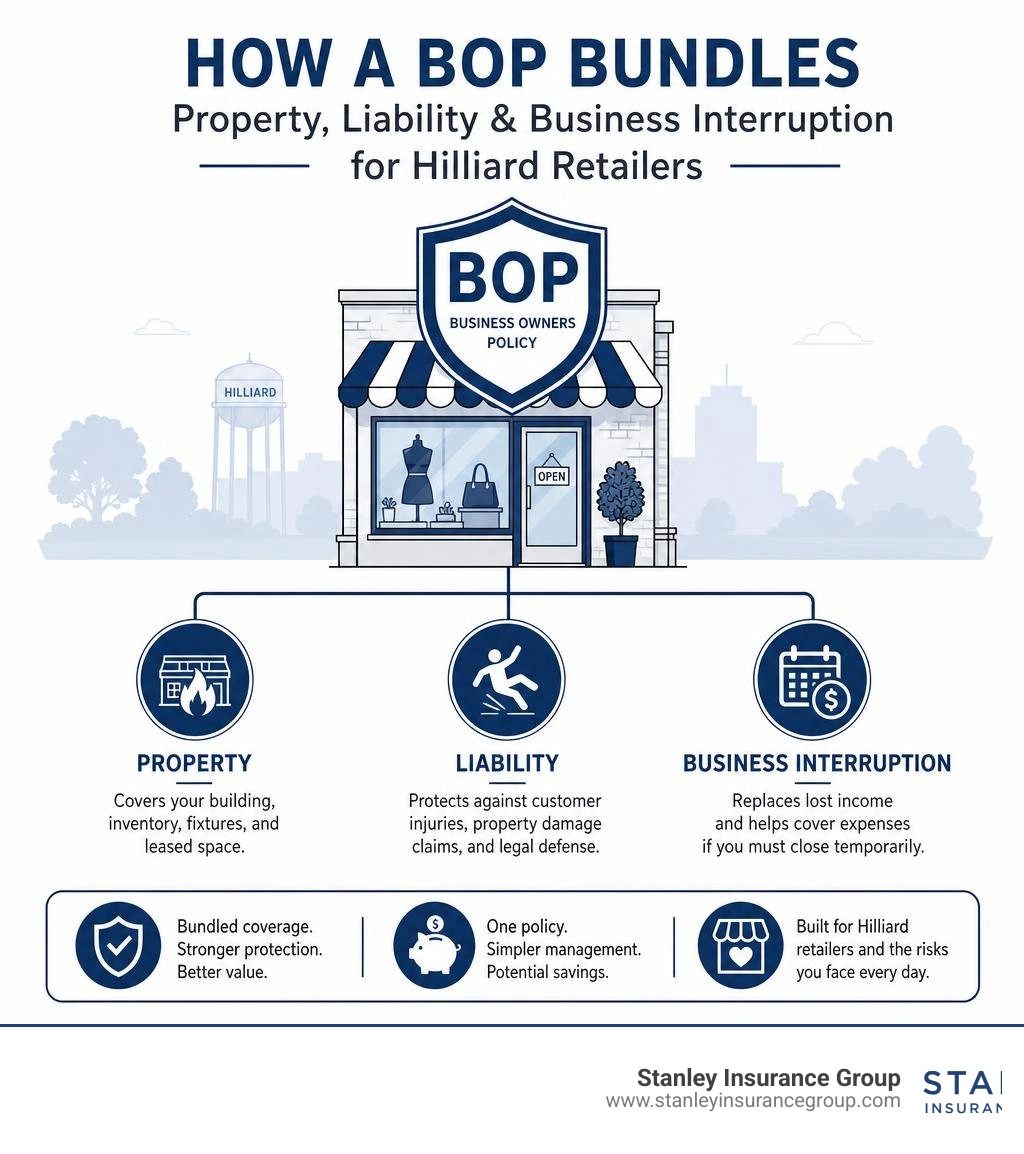
When we set up a Business Owners Policy or a broader Business Owners Insurance Policy for our clients, we look at three core pillars:
- Commercial Property: Coverage for your physical storefront (if you own it), leased improvements, display racks, cash registers, and your entire inventory.
- General Liability: Protection if a customer claims they were injured on your premises or if you accidentally damage someone else's property.
- Business Interruption: A safety net that replaces lost income and covers ongoing expenses (like payroll and rent) if a covered fire, windstorm, or water leak forces your doors shut.
Several key factors affect your 2026 BOP pricing in Hilliard. Your product type (selling high-end jewelry vs. selling stationary), your exact location (such as a busy strip mall on Hilliard Rome Road vs. a quiet side street), your past claims history, and your active security controls (such as security cameras, alarms, and fire suppression systems) all play a massive role in what you pay.
Core Protections of a BOP for Retail Hilliard Businesses
Let's look closer at how these core protections handle real-world situations. First, there is General Liability. As we mentioned, Hilliard retail locations report a 12% higher incidence of slip-and-fall liability claims compared to the national average for similar-sized communities. Whether it is a slushy winter afternoon where Ohio snow melts all over your entryway, or a minor spill near your displays, a single slip-and-fall lawsuit can easily cost tens of thousands of dollars in legal fees and medical bills.
Under the general liability portion of your BOP, these medical expenses, legal defense fees, and court settlements are covered. This is the cornerstone of protecting your cash flow from unexpected customer-facing accidents.
Equally vital is Commercial Property Insurance. This coverage handles the physical realities of running a shop. If a pipe bursts behind your drywall during a brutal Ohio cold snap, or if a storm damages your roof, your property coverage steps in to pay for the repairs to the building and your business personal property. For a deeper dive into how Ohio regulations and local factors shape these policies, check out our General Liability Insurance Ohio Guide 2026.
Retail-Specific Risks and Inventory Management in Central Ohio
Retailers face risks that other businesses simply do not have to worry about. A consultant or accountant might only have a laptop and a desk to protect, but a retailer has thousands of dollars in physical merchandise sitting on shelves and in backrooms.
Retail businesses in Ohio face an average of 2.3 property claims per year, with theft and water damage being the most common causes. Whether it is shoplifting, organized retail crime, or a sudden plumbing leak that ruins your backroom storage, your inventory is constantly exposed to risk.
This makes proper inventory valuation critical. Many business owners make the mistake of setting their property limits based on their average stock levels. However, if your inventory spikes during the winter holidays or special local events, you could find yourself severely underinsured right when your stock is at its highest value.
We see this dynamic with major retail movements across Central Ohio. For example, when a new retail location opens, such as when pOpshelf Opens in Hillard, Ohio! | Anchor Retail, their initial stocking and grand opening phases represent massive inventory concentrations. If your policy limits do not reflect those peak times, a major loss during your busiest month could leave you paying out of pocket for the difference.
Managing Seasonal Stock Spikes and Off-Site Storage
To avoid this trap, Hilliard retailers should utilize "peak season endorsements" within their BOP. This feature automatically increases your business personal property limits by a set percentage (usually 25%) during your busiest months of the year, protecting your seasonal stock spikes without forcing you to pay for high limits year-round.
Additionally, many Hilliard shop owners use off-site storage units or temporary warehouses to hold extra inventory. Standard property coverage often limits protection to your primary business address. If you move stock off-site without notifying your agent, that inventory may have little to no coverage.
To make sure you are fully protected, we recommend completing a comprehensive Business Insurance Risk Assessment to identify where your stock travels. Knowing exactly What is Covered by Commercial Insurance ensures that whether your products are on your showroom floor, sitting in a local warehouse, or in transit, your assets remain secure.
Navigating Landlord Requirements and Certificates of Insurance (COIs)
If you lease a retail space in Hilliard — whether in a bustling shopping center, a historic building downtown, or a mixed-use development — your landlord will require you to show proof of insurance before you can pick up your keys. They do this by demanding a Certificate of Insurance (COI).
A COI is a single-page document that summarizes your active insurance coverages, policy limits, and effective dates. Landlords use these documents to protect themselves from being held liable for accidents that occur inside your leased space. If you cannot provide a clean, compliant COI, you could face lease violations, delayed openings, or even eviction. For a full breakdown of how these liability structures work, you can read our Business Liability Insurance Complete Guide.
Understanding COI Wording for Hilliard Retail Locations
Landlords and property managers are highly specific about the language they want to see on your COI. There are three key legal terms you will almost always encounter in a commercial lease agreement:
- Additional Insured: This status extends your liability coverage to the landlord. If a customer slips in your shop and sues both you and the landlord, your insurance policy will defend the landlord as well.
- Primary & Non-Contributory: This wording ensures that your insurance policy pays out first in the event of a claim, and your landlord's own insurance policy will not have to contribute to the loss.
- Waiver of Subrogation: This prevents your insurance carrier from suing your landlord to recover funds paid out for a claim, even if the landlord was partially at fault.
Satisfying these strict lease requirements is much easier when you work with an experienced Business Liability Insurance Broker Guide. We help local business owners tailor their BOP endorsements so that the COI matches the landlord’s lease requirements perfectly.
This is standard practice for any commercial tenant in our area, from boutique retail stores to popular local dining spots like those looking to Find Healthy Asian Bowls at BIBIBOP Hilliard Rome. Landlords want to know that if something goes wrong, the tenant's policy is fully prepared to handle the fallout.
When to Add Endorsements or Stand-Alone Policies
While a standard BOP provides an incredible foundation, it is not a magic shield that covers every single risk. Retail is changing rapidly, and some of the fastest-growing threats to your business require specialized endorsements or stand-alone policies.
One of the most pressing threats is cyber crime. Cyber liability incidents affecting retail businesses increased by 42% in Ohio between 2023 and 2025. If you use a modern Point of Sale (POS) system, collect customer emails, store credit card details, or run an e-commerce website alongside your physical storefront, you are a target. A standard BOP does not cover the costs of data breaches, ransom demands, or notifying affected customers. Adding a cyber liability endorsement is an absolute must in 2026.
Other critical additions to consider include:
- Equipment Breakdown: Covers the cost to repair or replace vital systems (like your HVAC unit, specialized POS servers, or security systems) if they suffer a sudden mechanical breakdown.
- Employment Practices Liability Insurance (EPLI): Did you know that three out of five small businesses are estimated to be sued by an employee at some point? EPLI protects you against claims of wrongful termination, discrimination, or sexual harassment.
- Commercial Umbrella: If a major claim exceeds your standard BOP liability limits, an umbrella policy provides an extra layer of protection, typically offering limits from $2,000,000 to $10,000,000.
To learn more about how these coverages fit together in the Central Ohio market, check out our resources on Small Business Insurance Columbus Ohio and explore Business Liability Insurance Ohio Cost.
Tailoring Your BOP for Retail Hilliard Operations
Every retail shop is unique. A local bookstore has different risks than a convenience store or a specialized boutique. That is why a cookie-cutter, online-only insurance policy often leaves dangerous gaps.
By utilizing custom endorsements, you can build a policy that fits your exact daily operations. For example, if you handle a high volume of credit card transactions, custom cyber endorsements protect you against POS cyber incidents. If you rely on specialized refrigeration or display lighting, equipment breakdown coverage keeps your doors open.
Taking the time to build a customized policy through a local agent ensures you are not paying for coverage you do not need, while fully protecting the areas where your business is most vulnerable. We highly recommend reviewing our guides on BOP for Small Business Hilliard and How to Choose the Best Business Insurance for Your Company to start building your custom protection plan.
Frequently Asked Questions About Retail BOPs in Hilliard
How much can a Hilliard retailer save by bundling coverages into a BOP?
On average, Hilliard retailers can save between 15% and 25% by bundling their commercial property and general liability policies into a single Business Owners Policy (BOP). Beyond the direct financial savings, bundling simplifies your administration by giving you a single renewal date, one premium payment, and one point of contact for claims. To understand exactly what is included in these package policies, read our guide on What is Covered by Standard Commercial Insurance.
What happens if my retail store experiences a major uninsured loss?
The statistics are sobering: over 60% of small retail businesses in the U.S. that experience a major loss without adequate insurance never reopen. Whether it is a devastating fire, prolonged water damage, or a massive liability lawsuit, the out-of-pocket costs can quickly drain your cash reserves and force you into bankruptcy. A robust BOP acts as your safety net, providing the commercial property, liability, and business interruption coverage needed to rebuild and reopen. Explore your options further on our Business Insurance page.
How quickly can I get a Certificate of Insurance (COI) for my lease?
At Stanley Insurance Group, we understand that time is money when you are trying to open a new retail location or renew a lease. In most cases, we can issue a Certificate of Insurance (COI) the same day you request it, provided we have all your lease requirements and policy details in hand. To speed up the process, make sure to send us the exact insurance section of your lease agreement so we can ensure all required wording is present. Ready to get started? You can Get a Quote online today.
Conclusion: Partnering with a Local Independent Agency
When it comes to protecting your livelihood, you shouldn't have to rely on a generic, 1-800 customer service line. At Stanley Insurance Group, we have been serving Central Ohio families and businesses since 1984. As a family-owned, independent agency with over 40 years of tenure in the Hilliard community, we believe in building real, lasting relationships with our clients. We offer that personal, concierge touch that captive or chain agencies simply cannot match.
Because we are an independent agency, we do not work for a single insurance company — we work for you. We can shop your coverage across 20+ of the nation's top carriers (including Nationwide, Progressive, Travelers, Liberty Mutual, Grange, and Safeco) to find the absolute best policy and price for your business. In fact, we are proud to be one of only 100 independent agencies in the entire country with a direct partnership with Geico, giving our clients access to highly exclusive commercial options.
Our dedicated team is here to guide you every step of the way:
- Amy leads our Commercial Lines department, helping retailers design the perfect BOP.
- Ana and Sandra, our bilingual Account Specialists, provide dedicated Spanish-speaking help to ensure all members of our community feel fully supported.
- Kaisen, Ethan, and Chase, our Associate Agents, are always ready to answer your questions, update your policies, and issue fast, same-day COIs.
Do not leave your retail business exposed to unexpected risks. Let our family protect yours. Visit our Business Insurance page to learn more, or click here to Get a Quote and experience the Stanley Insurance Group difference today!
Similar posts