Everything You Need to Know About Professional Liability Insurance Hilliard
Protect your Hilliard business with professional liability insurance Hilliard—compare quotes and get tailored coverage from local experts today.
Why Professional Liability Insurance in Hilliard Matters for Your Business
Professional liability insurance Hilliard business owners rely on is one of the most overlooked — and most important — protections for any service-based company. If a client claims your advice, work, or service caused them financial harm, general liability insurance won't help you. That's where professional liability (also called errors and omissions, or E&O) steps in.
Quick answer for Hilliard professionals:
- What it covers: Client claims of negligence, errors, missed deadlines, incorrect advice, or failure to deliver services
- Who needs it: Consultants, accountants, IT firms, real estate agents, designers, healthcare providers, and any professional whose work directly impacts a client's finances
- Why it matters: A single claim can average $130,000 in legal defense and settlement costs — enough to close a small business
- Where to get it in Hilliard: An independent agency like Stanley Insurance Group can shop multiple carriers to find the right fit for your profession and budget
Even a small mistake — a missed filing deadline or an off-target recommendation — can trigger a lawsuit. And even weak claims require legal counsel, which disrupts cash flow fast.
I'm Brandon Stanley, President of Stanley Insurance Group, and since 1984 our family-owned agency has helped Hilliard businesses navigate exactly these kinds of risks, including professional liability insurance in Hilliard across dozens of industries. Let's walk through everything you need to know to compare your options and choose the right coverage.

What is Professional Liability Insurance (Errors & Omissions)?
At its core, professional liability insurance—frequently referred to as Errors and Omissions (E&O) insurance—is designed to protect your business from the financial fallout of professional mistakes. If your business provides a service, offers advice, designs solutions, or makes professional recommendations, you are making a promise to your clients. When a client feels you failed to deliver on that promise and they suffer a financial loss as a result, they can sue your business.
Unlike physical accidents, professional mistakes don't usually result in broken bones or damaged property. Instead, they result in economic harm. For example, if an IT consultant in Hilliard fails to configure a database correctly, leading to a system outage that costs a client thousands of dollars in lost sales, that is an economic loss.
To help protect your business from these unique exposures, securing a dedicated Professional Liability Insurance policy is essential. It ensures that when errors occur, your legal defense costs, court fees, and any eventual settlements or judgments are covered, keeping your business assets secure.
To help visualize how this fits into your broader risk management strategy, here is a quick comparison of how professional liability stacks up against standard general liability coverage:
| Feature | General Liability Insurance | Professional Liability (E&O) Insurance |
|---|---|---|
| Primary Protection Focus | Physical and tangible damages | Financial and economic losses |
| Core Triggers | Bodily injury, property damage, personal/advertising injury | Negligence, mistakes, omissions, misrepresentation, missed deadlines |
| Example Scenario | A client slips on an icy sidewalk outside your Hilliard office and breaks their wrist. | A consultant gives advice that results in a client losing a major contract. |
| Legal Defense Costs | Covered for physical injury/damage lawsuits | Covered for professional negligence and service errors |
| Who Needs It? | Virtually every business with a physical presence or customer interaction | Any business providing specialized services, advice, or intellectual work |
Key Differences from General Liability Insurance
It is a common and highly expensive mistake for business owners to assume that a standard Commercial General Liability (CGL) policy covers all liabilities. A CGL policy is designed to handle "slips, trips, and falls." It acts as a safety net if a customer trips over a loose cord in your lobby or if you accidentally spill coffee on a client's expensive laptop.
However, general liability specifically excludes coverage for professional mistakes, faulty advice, or failure to deliver promised results. If a client sues you because your marketing campaign featured a typo that ruined their brand's reputation, or because your engineering plan contained a calculation error, your general liability policy will not pay a single dime toward your defense.
For a deeper dive into how these coverages interact and protect your entire operation, you can consult our Business Liability Insurance Complete Guide. Understanding the dividing line between physical damages and economic losses is the first step toward building an airtight risk management plan.
Why Your Business Needs Professional Liability Insurance Hilliard
Hilliard, Ohio is a dynamic and rapidly growing business community. From the bustling professional offices along Cemetery Road to the home-based consulting firms operating near Old Hilliard, local business owners face unique challenges. In our highly litigious environment, even a minor oversight can quickly escalate into a devastating lawsuit.
Industry data reveals that professional liability claims can cost businesses an average of $130,000 per claim in legal defense and settlement costs. For a small business or solo practitioner in Central Ohio, writing a check for that amount out of pocket is simply not feasible. In fact, over 50% of small businesses that face a professional liability lawsuit without coverage go out of business within a single year.
Furthermore, having professional liability coverage is often a strict contractual requirement. Many corporate clients, government entities, and large partners in the Columbus metro area will not sign a contract with you unless you can provide a Certificate of Insurance (COI) proving you carry E&O coverage.
To understand how these risks affect your bottom line locally, you can explore our resources on Business Liability Insurance Ohio Cost. Protecting your business isn't just about surviving a worst-case scenario; it’s about positioning your company to win larger contracts and build trust in the community. As a dedicated local partner, Our Independent Insurance Agency Serves Hilliard, Ohio Residents by tailoring coverages specifically to our local regulatory and economic landscape.
Who Needs Professional Liability Insurance Hilliard?
If your business relies on your unique expertise, specialized knowledge, or professional advice to make a living, you need professional liability insurance. This isn't just for doctors and lawyers; it applies to a wide range of modern service industries.
Some of the most common professions in Hilliard and Central Ohio that require E&O coverage include:
- Business and Management Consultants: If your strategic advice fails to produce the promised results or causes a client to lose money, you could be held liable.
- Accountants, Bookkeepers, and Tax Preparers: A single misplaced decimal point or a missed tax filing deadline can result in massive IRS penalties for your client.
- IT Professionals and Software Developers: Code errors, system recommendation failures, or missed project deadlines can paralyze a client's business operations.
- Real Estate Agents and Brokers: Failing to disclose a property defect or making an error in a contract can lead to expensive lawsuits from disgruntled buyers.
- Marketing Agencies and Graphic Designers: Copyright infringement claims, printing errors, or missed campaign launches can cause significant financial harm.
Service industries such as consulting, accounting, and IT are actually three times more likely to face E&O claims than other business sectors. To learn more about how local Columbus and Hilliard businesses protect themselves, check out our guide on Small Business Insurance Columbus Ohio. Additionally, for healthcare and specialized business professionals, exploring career-targeted solutions like those found at Professional Liability Insurance Coverage Built For Your Career | Proliability can provide valuable insights into occupation-specific risks.
Common Claims and Real-World Scenarios
To understand how easily a professional liability claim can arise, let's look at a few realistic scenarios that local service providers might face:
- The Missed Deadline: A freelance IT developer in Dublin, OH is contracted to build an e-commerce platform ahead of a client's critical holiday shopping launch. Due to unexpected coding delays, the site launch is pushed back by three weeks, causing the client to miss their peak sales window. The client sues the developer for lost revenue.
- The Inaccurate Projection: A financial consultant in Hilliard advises a local business owner to purchase high-priced manufacturing equipment based on inaccurate cash flow projections. When the business suffers a severe cash crunch due to the purchase, they sue the consultant for negligent advice.
- The Architectural Oversight: An architect makes a minor calculation error on a set of blueprints for a new commercial building in Arlington. During construction, the error is discovered, requiring a portion of the structure to be demolished and rebuilt, resulting in tens of thousands of dollars in delays and extra material costs.
Even if you did nothing wrong, the cost to prove your innocence in court can be astronomical. A standard Professional Liability policy ensures that you have the financial backing to defend your reputation. For additional context on how professional liability works across different Ohio regions, you can also review how coverage is structured in other parts of the state, such as Professional Liability Insurance - Hillsboro, OH , or read about specialized commercial lines through resources like Professional Liability | Hilb Group .
Understanding Coverage, Exclusions, and Costs
When purchasing professional liability insurance Hilliard business owners must understand that these policies are highly customized. Unlike a standard auto policy, which has relatively uniform terms, an E&O policy must be carefully tailored to your specific industry, business size, and risk exposure.
Most professional liability policies are written on a "claims-made" basis. This means the policy must be active both when the alleged mistake occurred and when the claim is officially filed. If you cancel your policy and a client sues you two months later for work you did last year, you will not have coverage unless you purchased an extended reporting period (often called "tail coverage").
Before securing a policy, conducting a thorough Business Insurance Risk Assessment is crucial to identifying your specific vulnerabilities and choosing the right policy limits and deductibles.
What is Typically Excluded?
While professional liability insurance provides broad protection for errors, omissions, and negligence, it is not a catch-all policy. Every insurance contract has specific exclusions that you must be aware of to avoid dangerous gaps in your protection.
Common exclusions in a professional liability policy include:
- Intentional Dishonesty and Fraud: If you intentionally deceive a client or commit a criminal act, your insurance will not cover you.
- Bodily Injury and Property Damage: As discussed, these risks belong under your general liability policy.
- Cyber Breaches and Data Theft: While some E&O policies offer cyber endorsements, standard professional liability does not cover the costs of a data breach. You need dedicated cyber liability insurance for that.
- Employment Practices: Claims related to wrongful termination, discrimination, or sexual harassment are excluded and require Employment Practices Liability Insurance (EPLI).
Many small business owners in Hilliard choose to manage these overlapping risks by utilizing a BOP for Small Business Hilliard. A Business Owners Policy bundles general liability, property insurance, and other essential coverages into a single, cost-effective package, which can then be supplemented with a professional liability endorsement.
Factors That Influence Your Premium
Because professional liability risks vary wildly from one industry to another, there is no "one-size-fits-all" premium. An insurance carrier looks at several key risk factors when determining your premium:
- Your Industry and Profession: A structural engineer or a medical provider faces significantly higher risks of severe financial or physical consequences from an error than a graphic designer or a resume writer.
- Your Business Revenue: Higher revenue typically correlates with larger contracts, which means larger potential claims if something goes wrong.
- Your Claims History: A track record of past lawsuits or claims will signal higher risk to underwriters, leading to higher premiums.
- Your Location: Operating in a high-litigation area or a fast-growing metro like Central Ohio can impact rates.
- Your Policy Limits and Deductibles: Choosing higher coverage limits or a lower deductible will increase your premium, while opting for a higher deductible can lower your monthly costs.
To navigate these variables and structure a policy that fits your budget, working with a knowledgeable commercial specialist is highly beneficial. You can read more about how to navigate this process in our Business Liability Insurance Broker Guide.
How to Choose the Best Professional Liability Insurance Hilliard Policy
Choosing the right professional liability policy requires careful comparison. Because different carriers specialize in different industries, a policy that is perfect for an IT firm might be completely inadequate for an accounting practice.
When comparing policies, look closely at the definition of "professional services" in the policy language. This definition outlines exactly what activities are covered. If your business model has evolved and you are now offering services not listed in your policy, you may find yourself without coverage when a claim arises.
For a step-by-step roadmap on navigating this selection process, read our guide on How to Choose the Best Business Insurance for Your Company.
The Advantage of Working with an Independent Agency
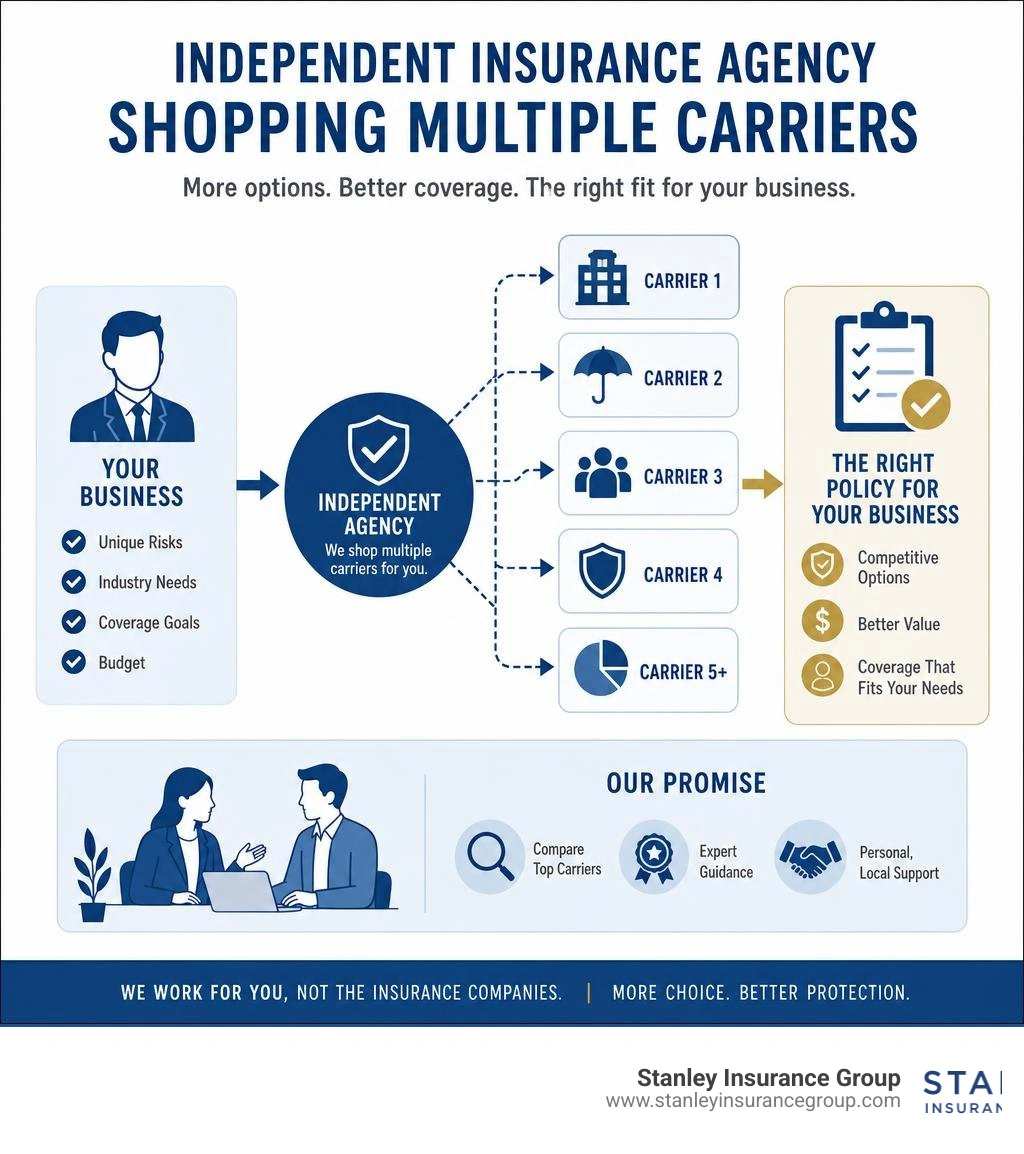
The absolute best way to secure the right coverage at the most competitive price is to partner with an independent insurance agency. Unlike captive agents who can only sell policies from a single insurance company, independent agents represent multiple carriers.
At Stanley Insurance Group, we shop your coverage across more than 20 of the nation's top insurance carriers. This allows us to compare policy features, limits, and rates to find the perfect match for your specific business. We combine this extensive carrier access with a personal, relationship-first approach—what we call our "concierge touch."
When you work with us, you aren't calling a 1-800 number to speak with a random call center representative. You are working with local professionals who live and work right here in Central Ohio. We take the time to build a genuine relationship with you, ensuring your business is fully protected as it grows.
Often, we can help you integrate your professional liability coverage with a broader Business Owners Policy to maximize your savings while eliminating dangerous gaps in your coverage.
Frequently Asked Questions About E&O Insurance
What is the average cost of professional liability insurance in Ohio?
Because professional liability insurance is highly customized, costs vary significantly based on your specific industry, business size, and coverage limits. A freelance graphic designer will pay a very different rate than a structural engineer or a medical practice. To get an accurate picture of what your business will pay, the best approach is to have an independent agent shop your specific risk profile across multiple carriers.
Is professional liability insurance legally required in Hilliard?
While the State of Ohio does not legally mandate professional liability insurance for most businesses, carrying it is often a practical necessity. Many professional licensing boards, industry associations, and corporate clients require proof of coverage. Furthermore, standard business contracts in Central Ohio frequently include clauses requiring you to maintain a minimum level of E&O coverage before you can begin work.
Can I bundle professional liability with a Business Owners Policy (BOP)?
Yes! Many insurance carriers allow you to add professional liability coverage to a Business Owners Policy (BOP) as an endorsement. Bundling your coverages this way is often much more cost-effective than purchasing separate, standalone policies. It also simplifies your administration by keeping your general liability, commercial property, and professional liability coverages under a single policy with one renewal date.
Conclusion: Secure Your Hilliard Business Today
Since 1984, Stanley Insurance Group has been a trusted, family-owned fixture in the Hilliard community. Over the past 40+ years, we have built our reputation on providing the kind of personal, relationship-driven service that captive or chain agencies simply cannot match. We don't just sell policies; we build lasting relationships with Central Ohio families and business owners.
As an independent agency, we work directly for you. We have the unique ability to shop 20+ top-rated carriers—including Nationwide, Progressive, Travelers, Liberty Mutual, Grange, Safeco, and more—to find the absolute best coverage at the most competitive price. In fact, we are one of only 100 independent agencies in the entire country to hold a direct partnership with Geico, giving us unparalleled flexibility in finding the right solutions for our clients.
Whether you need business insurance, home & property protection, auto coverage, or life insurance, our dedicated team is here to help. When you reach out to our office, you will work with real, local professionals:
- Amy manages our Commercial Lines division, helping Hilliard businesses navigate complex risks like professional liability.
- Ana and Sandra, our bilingual Account Specialists, are proud to offer dedicated Spanish-speaking help to our diverse Central Ohio community.
- Kaisen, Ethan, and Chase, our knowledgeable Associate Agents, are always ready to assist you with personalized service and expert advice.
Don't leave your business vulnerable to unexpected mistakes or costly lawsuits. Let our family protect yours. Contact us today to experience the concierge touch of an agency that has served Hilliard "Since '84."
Ready to protect your business? Get a Quote Today and let us do the shopping for you!
Similar posts