A Quick Start Guide to Business Owners Policy Ohio
Protect your Hilliard small business with a Business owners policy Ohio that bundles essential coverage and optional endorsements for complete protection.
What a Business Owners Policy in Ohio Actually Covers (And Why It Matters)
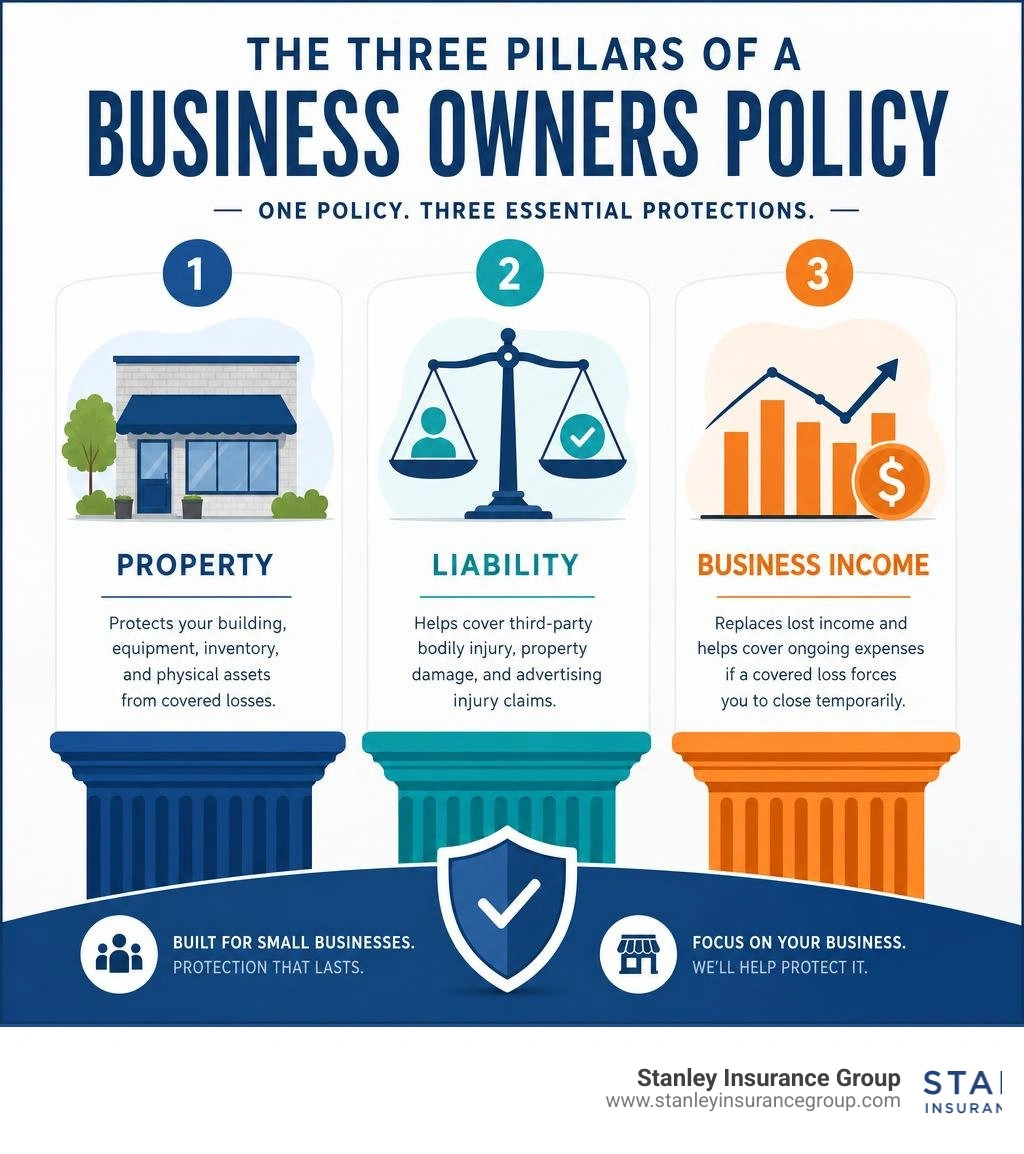
A business owners policy Ohio small business owners rely on is a bundled insurance package that combines three essential coverages into one affordable policy:
| Coverage | What It Protects |
|---|---|
| Commercial Property | Your building, equipment, inventory, and physical assets |
| General Liability | Third-party bodily injury, property damage, and advertising injury claims |
| Business Interruption | Lost income and ongoing expenses if a covered loss forces you to close temporarily |
Instead of buying three separate policies, a BOP packages them together — typically saving small businesses 20–30% compared to purchasing each coverage on its own.
Who typically qualifies? Small businesses with:
- Fewer than 100 employees
- Less than $5 million in annual revenue
- A physical location outside the home
Running a business in Ohio means juggling a lot — payroll, customers, operations. The last thing you need is a fire, a slip-and-fall lawsuit, or a break-in catching you without the right coverage. A BOP is designed to close that gap without overcomplicating your insurance.
I'm Brandon Stanley, President of Stanley Insurance Group, and since 1984 our family-owned agency has helped Ohio business owners find the right business owners policy in Ohio — shopping across 20+ top carriers to match the right coverage to each unique business. Let's walk through exactly how a BOP works and how to know if it's the right fit for yours.
What is a Business owners policy Ohio and How Does It Work?
For many business owners in Hilliard, Columbus, Dublin, and Arlington, managing risk can feel like trying to predict the Ohio weather—one minute it is sunny, and the next you are dealing with a sudden freeze. A business owners policy Ohio (commonly referred to as a BOP) acts as your company’s financial umbrella.
At its core, a BOP is a packaged commercial policy. Instead of forcing you to purchase, track, and pay for multiple standalone policies, it gathers the foundational protections every business needs under one single policy and one monthly bill. This includes safeguarding your physical workspace, protecting your business from costly third-party lawsuits, and providing a financial safety net if disaster strikes and forces you to close your doors temporarily.
By choosing a bundled approach, you gain simplified management and robust protection. To learn more about the fundamentals of this structure, you can read our detailed guide on the Business Owners Insurance Policy.
Core Coverages Included in a Standard BOP
A standard business owners policy Ohio relies on three primary pillars of protection:
- Commercial Property Insurance: This covers your physical building (if you own it) and everything inside it, including leased equipment, inventory, furniture, and computers. Whether you are dealing with fire damage, theft, or vandalism, this coverage helps pay to repair or replace your essential business assets. For a deeper look at protecting your physical assets, explore our guide on Commercial Property Insurance.
- General Liability Insurance: This protects your business if a customer, vendor, or visitor is injured on your property or if your operations cause damage to someone else's property. It also covers personal and advertising injury, such as libel, slander, or copyright infringement. For a complete breakdown of how this operates, check out our Business Liability Insurance Complete Guide.
- Business Interruption (Business Income) Insurance: If a covered property loss—such as a fire or severe windstorm—makes your physical location uninhabitable, business interruption coverage steps in. It helps cover lost net income, ongoing payroll, rent, and utility payments while your property is being rebuilt or repaired.
These coverages form the bedrock of a secure business. You can read more about how these protections combine by checking out the Ohio Business Owners Policy | PolicySweet resources.
Who Qualifies for a Business owners policy Ohio?
While a BOP is an incredible tool, it is not a one-size-fits-all solution for every enterprise. Insurance carriers design BOPs specifically for small- to mid-sized businesses operating in low- to moderate-risk industries.
To qualify for a standard business owners policy Ohio, your company typically must meet the following criteria:
- Employee Count: Generally fewer than 100 employees.
- Annual Revenue: Typically less than $5 million in annual sales.
- Location Size: Operating out of a physical commercial space, often with a square footage limit (such as under 25,000 square feet).
- Industry Type: Common eligible industries in Central Ohio include retail shops, professional offices (such as accountants, lawyers, and consultants), local restaurants, medical practices, salons, and service contractors.
If your business operates in a high-hazard industry—such as heavy manufacturing, auto repair, bars, or banks—you may need a customized Commercial Package Policy (CPP) instead. For local business owners in Hilliard, you can explore specialized local insights in our guide on BOP for Small Business Hilliard.
Customizing Your BOP with Optional Endorsements
One of the greatest benefits of a business owners policy Ohio is its flexibility. While the standard policy provides excellent baseline protection, every business in the Columbus metro area has unique risks. A retail store in Dublin has different exposures than a consulting firm in Arlington.
Fortunately, you can customize your BOP by adding specific endorsements—think of them as custom upgrades tailored to your unique operational risks.
To make sure you are selecting the right upgrades, it is highly beneficial to perform a thorough Business Insurance Risk Assessment with an experienced agent. This step ensures you don't pay for coverage you don't need, while closing critical gaps. For more context on local business protection, see our resource on Small Business Insurance Columbus Ohio.
Cyber Liability and Equipment Breakdown
In our highly digital world, physical damage is no longer the only threat to your daily operations.
- Cyber Liability (Data Breach Coverage): If your business stores sensitive customer data, credit card information, or medical records, you are a target for cybercriminals. Cyber liability endorsements help cover the cost of data forensic investigations, legal fees, public relations efforts, and state-mandated customer notification processes following a breach.
- Equipment Breakdown Coverage: Standard property insurance covers external damage (like a fire), but it typically excludes internal mechanical or electrical failures. Equipment breakdown coverage protects your essential systems—such as HVAC units, commercial refrigerators, computer servers, and specialized machinery—from losses caused by power surges, mechanical failures, or boiler explosions.
To understand how these modern endorsements integrate into your broader commercial strategy, you can review the Ohio Business Insurance | Progressive Commercial details.
Hired and Non-Owned Auto (HNOA)
Do your employees ever use their personal vehicles to pick up office supplies, deliver food, or drive to client meetings in Arlington? If so, your business faces a major liability gap.
If an employee gets into a car accident while performing a work-related task, their personal auto insurance may deny the claim, and the injured party could sue your business directly. Hired and Non-Owned Auto (HNOA) coverage is an endorsement that can be added to your BOP to provide liability protection for vehicles your business rents, leases, or allows employees to use for business purposes.
For more information on how this fits into your overall transportation risk management, visit our Commercial Auto Insurance page.
Key Exclusions: What a BOP Does Not Cover
While a business owners policy Ohio is remarkably comprehensive, it is equally important to understand what it cannot cover. Assuming your BOP covers every possible scenario is one of the most common mistakes we see when reviewing existing coverages for local business owners.

Understanding these boundaries is a core part of learning What is Covered by Commercial Insurance and identifying where you might need separate, specialized policies.
Workers' Compensation and Professional Liability
Two of the most significant exclusions from any standard BOP are workers' compensation and professional liability.
- Workers' Compensation: In Ohio, workers' compensation is strictly regulated. If you have even one employee, you are legally required to carry workers' compensation insurance. Because Ohio is a monopolistic state, this coverage must be purchased directly through the state fund and cannot be packaged inside a standard BOP.
- Professional Liability (Errors & Omissions): A BOP covers physical slip-and-fall accidents, but it does not cover financial damages caused by professional mistakes, negligence, or bad advice. If you are an accountant, consultant, or real estate agent in Dublin, you need a separate policy to protect your intellectual services. Learn more about this crucial protective layer on our Professional Liability Insurance page.
Commercial Auto and Flood Exclusions
Other common exclusions that require separate coverage lines include:
- Commercial Auto Insurance: If your business owns, leases, or operates vehicles registered in the business's name (such as delivery vans, utility trucks, or company cars), a standard BOP will not cover them. You must secure a dedicated commercial auto policy. For a deep dive into this topic, refer to our Commercial Auto Insurance Complete Guide.
- Flood and Earthquake Damage: Just like standard homeowners policies, commercial property insurance within a BOP excludes damage caused by floods, surface water, or earth movement. If your property is located near a flood zone in Central Ohio, you will need a separate commercial flood policy.
For a broader perspective on standard exclusions and state-level guidelines, you can read the Columbus, OH Business Insurance: General Liability & More resources.
Evaluating Costs and Standalone Policy Differences
When deciding how to structure your commercial protection, you generally have two paths: purchasing a bundled business owners policy Ohio or buying standalone policies for each individual exposure.
| Feature | Business Owners Policy (BOP) | Standalone Policies |
|---|---|---|
| Coverage Structure | Bundled (Property, Liability, & Business Income) | Separate, individual policies |
| Cost Efficiency | High (Bundling discount of 20-30%) | Standard (No bundled discount) |
| Administrative Effort | One policy, one premium, one renewal date | Multiple bills, multiple renewal dates |
| Customization | Via endorsements | Highly customizable individual limits |
| Target Audience | Small- to mid-sized, low-to-moderate risk | Large, complex, or high-risk operations |
How Much Does a Business owners policy Ohio Cost?
Because every business is completely unique, there is no single flat rate for a BOP. Instead, insurance carriers evaluate several key risk factors to calculate your premium:
- Your Industry: A quiet consulting office in Hilliard carries far less physical risk than a bustling restaurant in Columbus with open flames and heavy foot traffic.
- Your Location: The age of your building, local crime rates, and proximity to fire departments in Central Ohio play a major role.
- Your Revenue and Payroll: Larger operations with higher sales volumes generally carry higher liability exposures.
- Your Building's Construction: Masonry buildings are often less expensive to insure than wood-frame structures due to fire resistance.
- Your Deductible: Choosing a higher deductible will lower your monthly premium, though you will pay more out-of-pocket in the event of a claim.
To learn more about the financial side of commercial liability coverage, take a look at our guide on Business Liability Insurance Ohio Cost.
BOP vs. Standalone General Liability and Property Policies
If you were to buy commercial general liability and commercial property insurance as separate standalone policies, you would miss out on significant packaging discounts. On average, bundling these coverages into a single BOP is 10 to 20 percent less expensive than purchasing them separately.
Beyond direct cost savings, a BOP simplifies your administrative life. You only have to manage one policy document, pay one bill, and work with a single carrier if you ever need to file a claim. If you want to compare how to structure these policies, our Business Liability Insurance Broker Guide can help you navigate the process.
Frequently Asked Questions About Ohio BOPs
Is a BOP legally required in Ohio?
No, the state of Ohio does not legally mandate that businesses carry a Business Owners Policy. However, you may find that it is practically required by third parties. Landlords in Columbus and Dublin almost always require commercial tenants to show proof of general liability insurance before signing a lease. Similarly, banks and lenders will require commercial property insurance before securing a business loan.
Can I add workers' compensation to my BOP?
No. Because Ohio is a monopolistic state, all workers' compensation must be obtained directly through the Ohio Bureau of Workers' Compensation (BWC). It cannot be added as an endorsement to a private commercial insurance policy like a BOP.
What is the difference between a BOP and a Commercial Package Policy (CPP)?
While both policies bundle coverages, a BOP is a pre-packaged policy designed for small, lower-risk businesses with simplified pricing. A Commercial Package Policy (CPP) is designed for larger, more complex, or higher-risk businesses that require highly customized coverage limits and specialized terms.
Conclusion: Let Stanley Insurance Group Protect Your Vision
Since '84, Stanley Insurance Group has been helping Central Ohio families and businesses secure what matters most. As an independent agency based in Hilliard, we don't work for a single insurance brand—we work directly for you.
We bring a true concierge touch to the commercial insurance process, building lifelong relationships with our clients. We shop your coverage across 20+ top-rated carriers—including Nationwide, Progressive, Liberty Mutual, and Grange—to find the absolute best coverage fit for your budget. In fact, we are proud to be one of only 100 independent agencies in the entire country with a direct partnership with Geico, giving our clients access to unmatched commercial solutions.
Whether you are looking to secure a new business owners policy Ohio or want to review your current commercial portfolio, our dedicated team is here to help. Our commercial lines are managed by Amy, and we have Spanish-speaking help readily available through our account specialists, Ana and Sandra. You can also work directly with our associate agents, Kaisen, Ethan, and Chase, to find the perfect fit.
Ready to protect your business with a team that has served Hilliard and Central Ohio for over 40 years? Explore our Business Insurance solutions today or contact us to start building a relationship that secures your company's future.
Similar posts