How to Find Cheap Business Insurance Hilliard Entrepreneurs Actually Trust
Discover the Best small business insurance Hilliard offers. Get essential coverage, save on premiums & protect your business today!
Why Finding the Best Small Business Insurance Hilliard Has to Offer Is Harder Than It Looks
The best small business insurance Hilliard entrepreneurs can rely on comes down to a handful of trusted local providers who understand Ohio's specific coverage requirements and the real risks facing businesses in this fast-growing Columbus suburb.
Quick answer — top coverage types Hilliard small businesses need most:
| Coverage Type | What It Does |
|---|---|
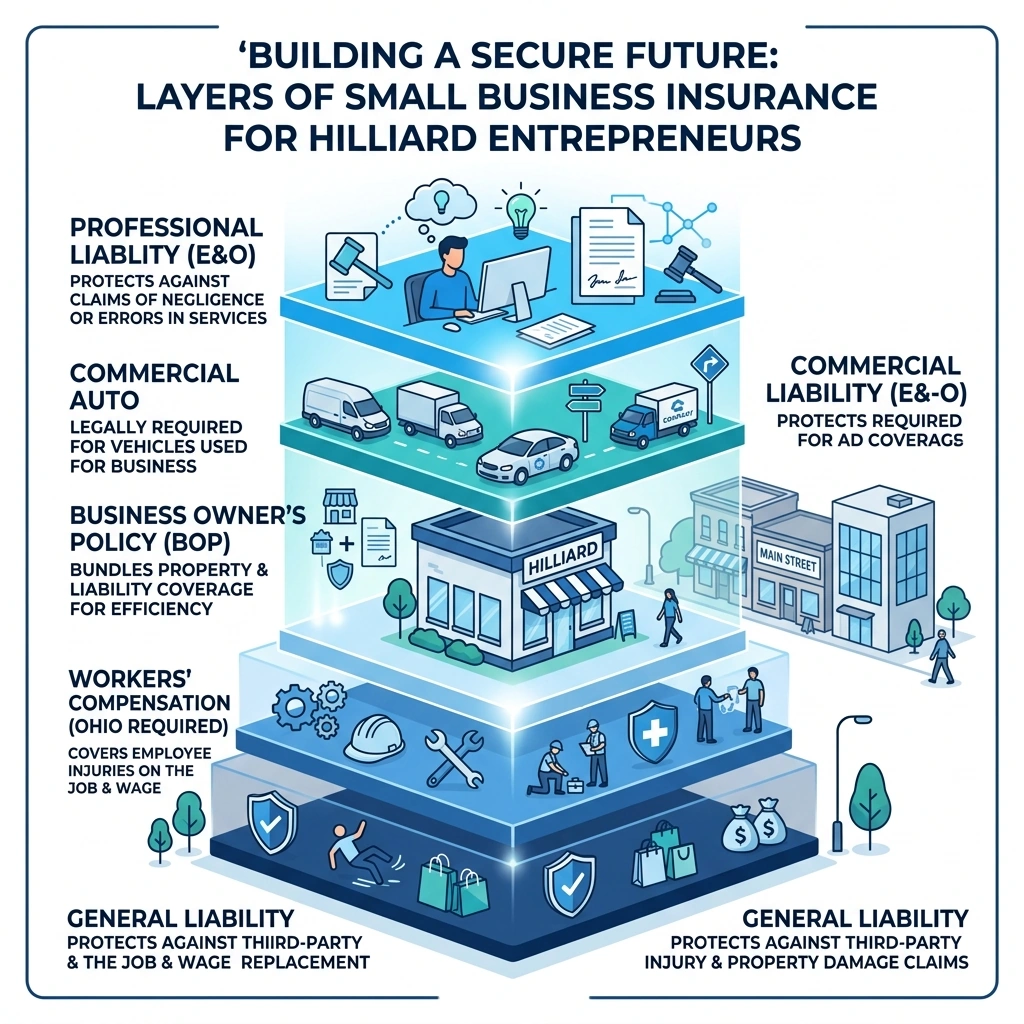
| General Liability | Covers third-party injury or property damage claims |
| Business Owners Policy (BOP) | Bundles property + liability for qualifying small businesses |
| Workers' Compensation | Required by Ohio law if you have employees |
| Commercial Auto | Legally required for any vehicle used for business purposes |
| Professional Liability | Protects against claims tied to advice or services |
Running a small business in Hilliard means navigating real risks every day — from slip-and-fall claims at your storefront to vehicle accidents on I-270. And yet, many business owners carry the wrong coverage, too little of it, or pay more than they should.
The good news? A local independent agency can shop multiple carriers, match coverage to your actual business, and stay with you when a claim happens — rather than handing you off to a call center.
At least 25% of businesses that close after a major disaster like a flood never reopen, according to FEMA. The right insurance policy isn't just paperwork. It's what keeps you in business.
I'm Brandon Stanley, President of Stanley Insurance Group — a family-owned independent agency serving Hilliard since 1984. Helping local entrepreneurs find the best small business insurance Hilliard has to offer has been a core part of what we do for over four decades. In the sections below, I'll walk you through exactly what coverage you need, what it costs, and how to avoid the most common mistakes business owners make.
Essential Coverage for the Best Small Business Insurance Hilliard Offers
When you are walking down Main Street or Cemetery Road, you see a vibrant mix of boutiques, offices, and service providers. Each one of those businesses faces a unique set of "what ifs." Finding the best small business insurance Hilliard provides means looking past the price tag and ensuring your specific risks are covered.

General Liability
This is the bedrock of any business policy. general liability protects you if a customer trips over a rug in your lobby or if you accidentally damage a client's property while working on-site. In a litigious world, having this shield is non-negotiable.
Commercial Property
Whether you own your building or rent a space near Old Hilliard, your physical assets need protection. commercial property insurance covers the structure itself, but also your inventory, equipment, and even the furniture inside. If a pipe bursts in the middle of a cold Ohio winter, this is the coverage that helps you dry out and move forward.
Professional Liability
If your business provides advice or specialized services—like an accountant, consultant, or IT professional—you need professional liability insurance. Often called Errors and Omissions (E&O), this protects you if a client claims your professional negligence caused them a financial loss.
Data Breach Protection
We live in a digital age. Even a small retail shop in Hilliard stores customer data. If that data is compromised, the costs of notification and credit monitoring can be staggering. A thorough business insurance risk assessment will often highlight the need for cyber coverage to protect your intellectual property and customer trust.
Understanding the Best Small Business Insurance Hilliard Requirements
In Ohio, "optional" is a word we don't get to use when it comes to certain coverages. Understanding why should i get commercial insurance in ohio starts with knowing the legal mandates.
Ohio Workers' CompensationOhio is one of the few "monopolistic" states, meaning all workers' comp insurance must be obtained through the Ohio Bureau of Workers' Compensation (BWC), unless you are self-insured. If you have even one employee, Ohio law requires you to have this coverage. It ensures that if a team member is injured on the job, their medical bills and lost wages are covered, while also providing employer liability protection for you.
Staying in legal compliance isn't just about avoiding fines; it's about protecting the people who help your business grow. Our team, including specialists like Amy who handles commercial lines, can help you navigate these BWC regulations so you never miss a filing.
Commercial Auto and Fleet Protection for Hilliard Roads
If you use a vehicle for any business purpose—whether it’s a dedicated floral delivery van or your personal truck used to haul tools to a job site—a personal auto policy likely won't cut it. In fact, if you’re in an accident while performing business duties, your personal insurance carrier could deny the claim entirely.
Ohio mandates minimum liability limits of 25/50/25 ($25,000 per person for bodily injury, $50,000 per accident for bodily injury, and $25,000 for property damage). However, for a business, these "state minimums" are rarely enough. One multi-car pileup on the I-270 loop during rush hour could easily exceed those limits, leaving your business assets vulnerable.
Our commercial auto insurance complete guide emphasizes the importance of higher limits. We also recommend looking into hired and non-owned auto coverage. This protects your business if an employee uses their own car to run a business errand—like picking up office supplies or dropping off a deposit—and gets into an accident.
Comparing BOP, General Liability, and Specialized Policies
For many Hilliard entrepreneurs, the most efficient way to get covered is through a business-owners-policy (BOP). Think of a BOP as the "Value Meal" of insurance—it bundles General Liability and Commercial Property into one convenient, and often discounted, package.
To be eligible for a BOP, businesses typically need to have:
- Fewer than 100 employees
- Less than $5 million in annual sales
- A low-risk business profile
BOP vs. Standalone General Liability
| Feature | Business Owners Policy (BOP) | Standalone General Liability |
|---|---|---|
| Property Coverage | Included (Buildings & Contents) | Not Included |
| Liability Coverage | Included | Included |
| Business Interruption | Often Included | Not Included |
| Cost | Generally Lower (Bundled) | Varies |
| Customization | Moderate | High |
A business owners insurance policy is excellent for retail shops and small offices, but some businesses with unique risks may need standalone policies or specific endorsements, such as equipment breakdown coverage for specialized machinery.
Industry-Specific Solutions for the Best Small Business Insurance Hilliard
Every industry has its own "ghosts in the machine." A restaurant faces different threats than a landscaping contractor.
- Contractors: Whether you are an electrician or a plumber, you likely move tools and equipment from site to site. You need Inland Marine insurance (don't let the name fool you—it has nothing to do with water) to cover your tools while they are in transit or at a job site.
- Restaurants: Beyond standard fire protection, Hilliard eateries need Liquor Liability if they serve alcohol. You also need to consider what is covered by standard commercial insurance regarding food spoilage if a walk-in freezer fails.
- Retail: High foot traffic means a higher risk of slip-and-fall incidents. Retailers also face unique risks related to shoplifting and employee dishonesty, which can be covered under Crime Insurance.
For businesses with significant assets, we often suggest commercial-umbrella-insurance. This provides an extra layer of liability protection that kicks in after your primary policy limits are reached.
How Much Does Business Insurance Cost in Hilliard?
"How much is this going to set me back?" It's the first question every owner asks. While we don't quote specific prices here (because every business is as unique as a fingerprint), we can look at the factors that drive business-liability-insurance-ohio-cost.
Several variables influence your premium:
- Industry Risk: A roofing contractor will naturally pay more than a bookkeeper because the physical risk is higher.
- Claims History: Just like with your personal car insurance, a clean history leads to better rates.
- Location: Being situated near high-traffic areas like I-70 or I-270 can impact your commercial auto rates due to the higher statistical likelihood of accidents.
- Payroll and Revenue: Larger operations with more employees or higher sales often require higher coverage limits.
When looking for a cheap commercial auto insurance guide, the key is not to sacrifice quality for price. The goal is to understand what is covered by commercial insurance so you aren't paying for "fluff" but are fully protected against the big disasters.
Strategies to Save on Your Commercial Premiums
We love helping our neighbors save money. Since '84, we’ve learned a few tricks to keep premiums down without leaving you exposed.
- Bundle and Save: This is the easiest win. Combining your business insurance with your personal auto or home policies often triggers significant multi-policy discounts.
- Implement Safety Protocols: Insurance companies love proactive owners. Having a formal safety manual, regular employee training, and well-maintained equipment can make you more "insurable" and lower your rates.
- Security Measures: Installing alarm systems, fire sprinklers, and security cameras can reduce your property insurance costs.
- Adjust Your Deductibles: Choosing a higher deductible can lower your monthly premium. Just make sure you have enough cash on hand to cover that deductible if a claim occurs.
- Work with an Independent Agent: This is our specialty. When you know how to choose the best business insurance for your company, you realize that a captive agent can only give you one price. We shop over 20 carriers to find the one that is currently "hungry" for your type of business.
You can explore more tips in our category/commercial-insurance blog section.
Frequently Asked Questions about Hilliard Business Insurance
Do I need insurance if I work from home in Hilliard?
Yes! Most standard homeowners' policies provide very limited coverage for business equipment and almost no liability coverage for business-related mishaps. If a delivery driver trips on your porch while dropping off a business package, your home insurance might not cover it.
How does Ohio Workers' Compensation differ from other states?
As mentioned, Ohio is a monopolistic state. You can't just "add it on" to your private package. You must coordinate with the Ohio BWC. However, we can help you understand how your BWC premiums interact with your private liability policies.
What factors affect my commercial auto rates near the I-270 loop?
Traffic density, local accident rates, and the distance your vehicles travel all play a role. If your vans are constantly navigating the "outerbelt," your risk profile is higher than a business that stays strictly within Hilliard city limits.
Conclusion: Choosing a Local Partner for Your Hilliard Business
At the end of the day, insurance is a promise. It’s a promise that when things go sideways, someone will be there to help you pick up the pieces.
At Stanley Insurance Group, we’ve been keeping that promise Since '84. We aren't a faceless 1-800 number. We are a family-owned independent agency that lives and works right here in Hilliard. We understand the local market because we are a part of it.
What makes us different?
- Independence: We shop 20+ top carriers like Nationwide, Travelers, Liberty Mutual, and Progressive.
- Exclusive Partnerships: We are one of only 100 independent agencies in the entire country with a partnership with Geico.
- The Concierge Touch: You’ll work with real people like Amy in Commercial Lines, or Kaisen, Ethan, and Chase.
- Spanish-Speaking Support: We want to make sure every entrepreneur in our community feels heard. Our account specialists, Ana and Sandra, are available to provide expert help in Spanish.
If you’re looking for small business insurance columbus ohio or specifically the best small business insurance Hilliard has to offer, let us do the heavy lifting for you. We’ll build a relationship first and a policy second.
Ready to protect your vision? Get a Quote today and experience the difference that 40 years of local expertise can make.
Similar posts